
Logistics
Can Your Business Handle 22% More Online Orders?

Logistics
CILT Conference to Explore Innovation and Cross-Border Connectivity at Automechanika Johannesburg
Transport reform, regional trade, safer freight corridors and workforce development will take centre stage at the Chartered Institute of Logistics and Transport (CILT) Namibia, South Africa and Zimbabwe Regional Conference at Automechanika Johannesburg on 28 and 29 October 2026.
Taking place at Gallagher Convention Centre in Midrand, the conference will explore the theme “Driving Innovation: Bridging Borders for an African Future”. Its programme brings together perspectives from government, industry, professional bodies and education to examine the transport, logistics and supply chain challenges shaping regional connectivity.
With Tiro Rapoo of NEXT Gen – an interest group of CILT – as programme director, the discussions will focus on how infrastructure, regulation, technology and skills can support a more connected African transport landscape, with an emphasis on practical regional challenges. Four panels will address transport corridors, cross-border harmonisation, safety and security, and education and training.
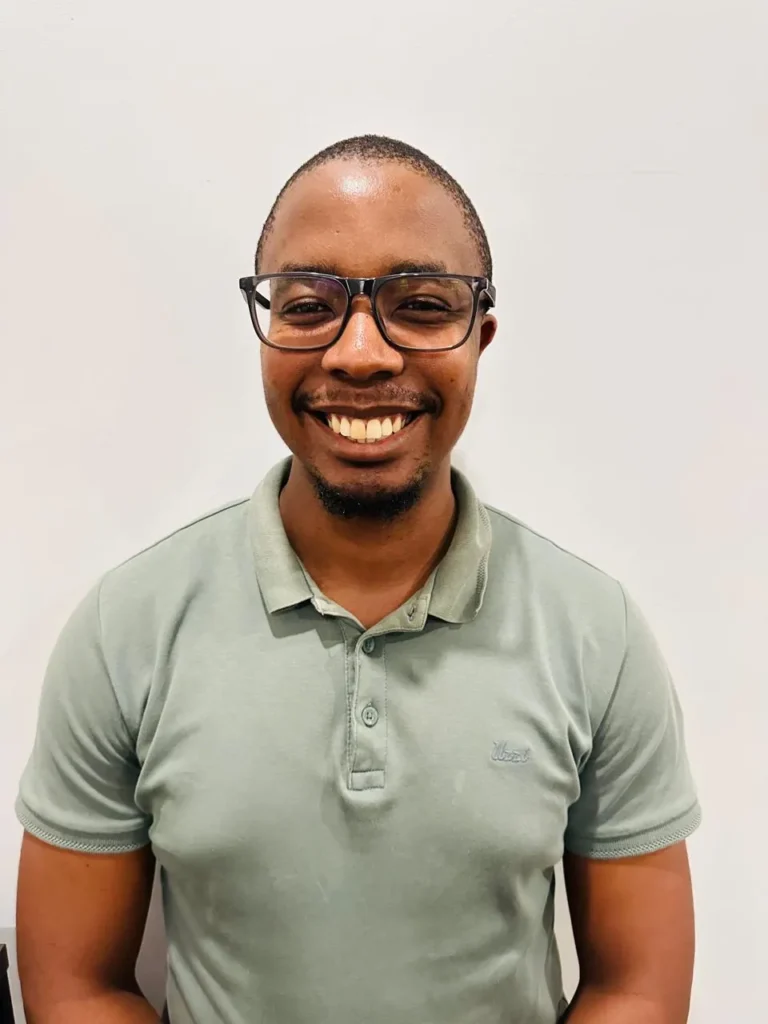
Tiro Rapoo of NEXT Gen
“By focusing on critical corridors, standardisation, safety, and future-ready skills, the programme is structured to deliver actionable solutions that help move goods and people across our borders more efficiently and securely,” says Elvin Harris, President of the Chartered Institute of Logistics and Transport South Africa (CILTSA).
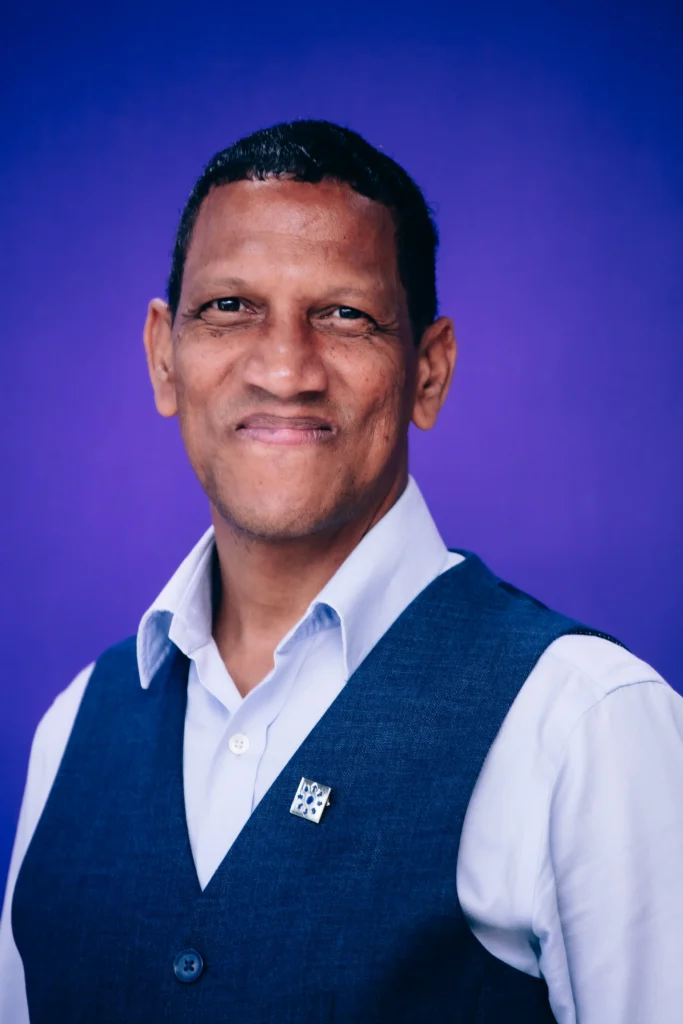
Elvin Harris, President of the Chartered Institute of Logistics and Transport South Africa (CILTSA).
Connecting Corridors and Aligning Systems
Lwazi Mboyi, CEO of the Cross-Border Road Transport Agency (C-BRTA), will address enabling cross-border road transport in Africa. Aneeqah Meyer, Manager at Ernst & Young Advisory Services, will examine economic integration, the African Continental Free Trade Area (AfCFTA) and the future of African trade.
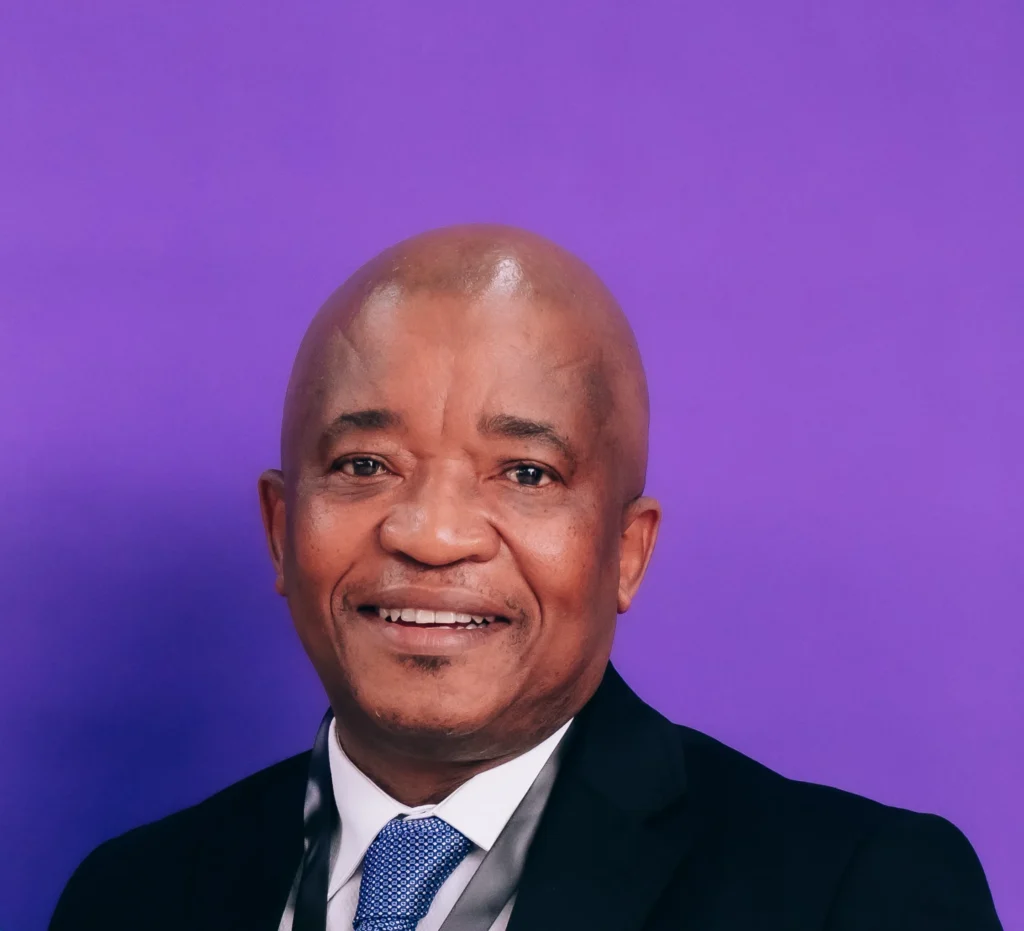
Lwazi Mboyi, CEO of the Cross-Border Road Transport Agency (C-BRTA)
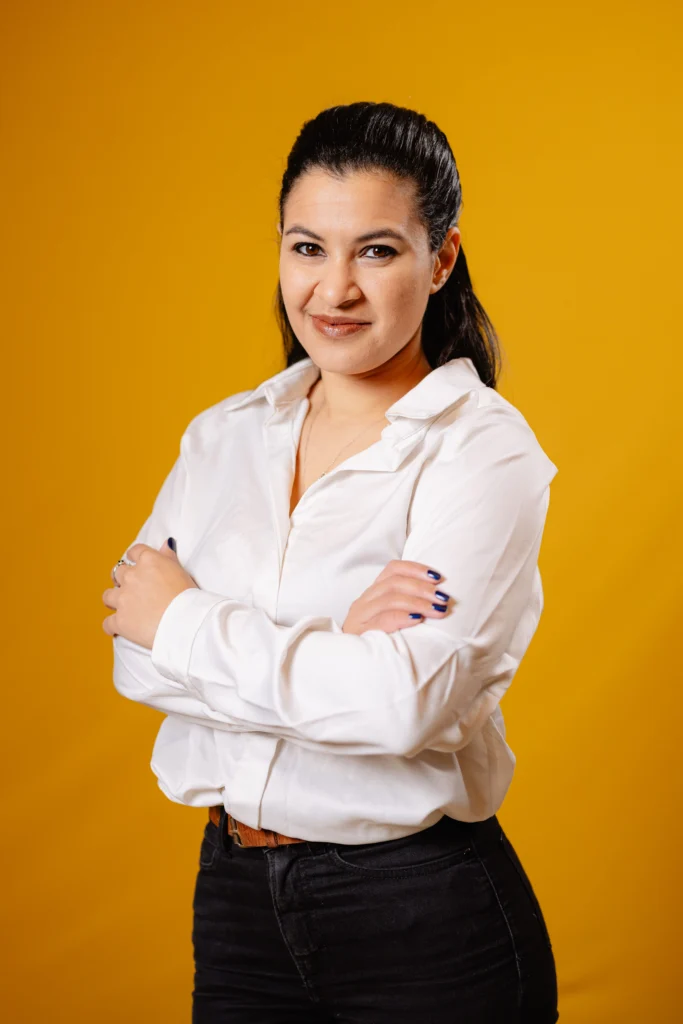
Aneeqah Meyer, Manager at Ernst & Young Advisory Services
The transport corridors panel will feature Crynos Mutendera, Senior Research Specialist at C-BRTA and Lebo Letsoalo, founder of the African Women in Supply Chain Association (AWISCA) and Sincpoint. Discussions will cover strategic road and rail corridors, reducing border delays and non-tariff barriers, and lessons from one-stop border posts. Infrastructure financing, the contribution of dry ports and inland terminals, and links between corridor development and regional industrialisation will also feature.
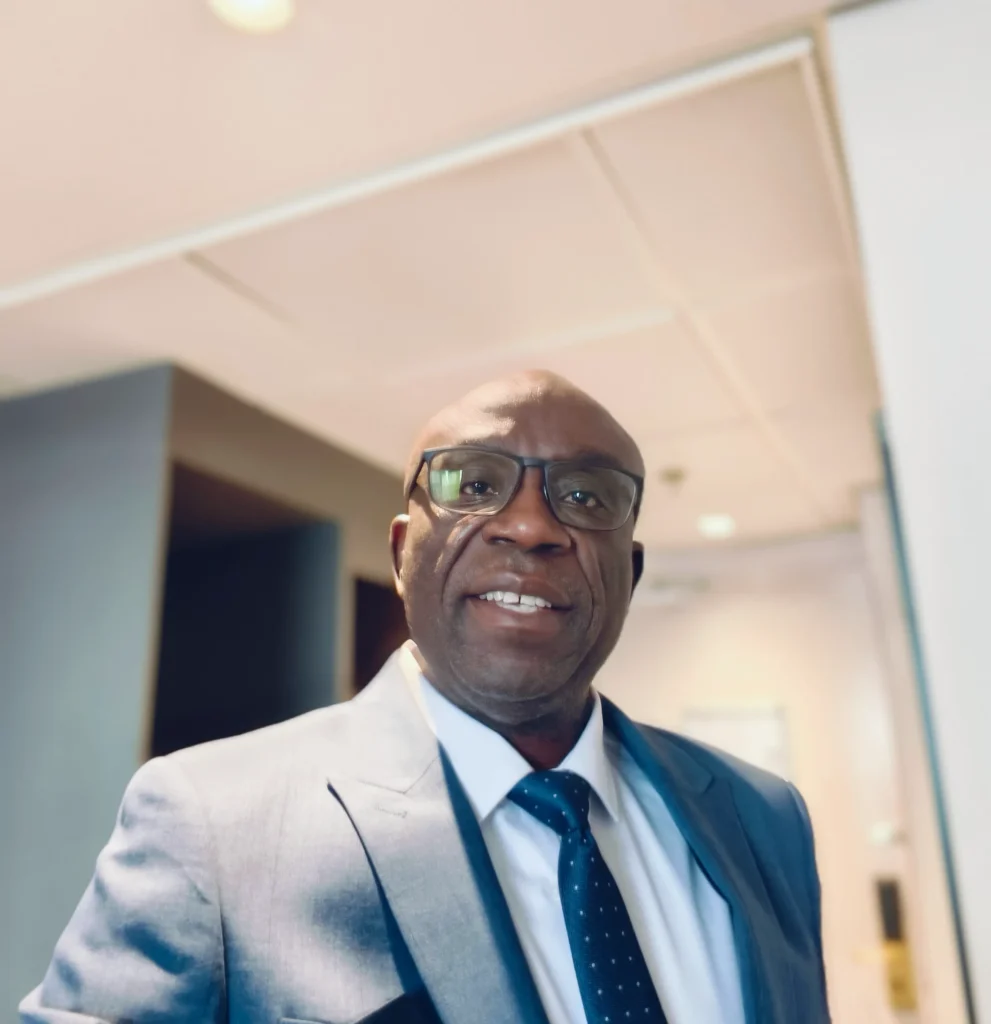
Crynos Mutendera, Senior Research Specialist at C-BRTA
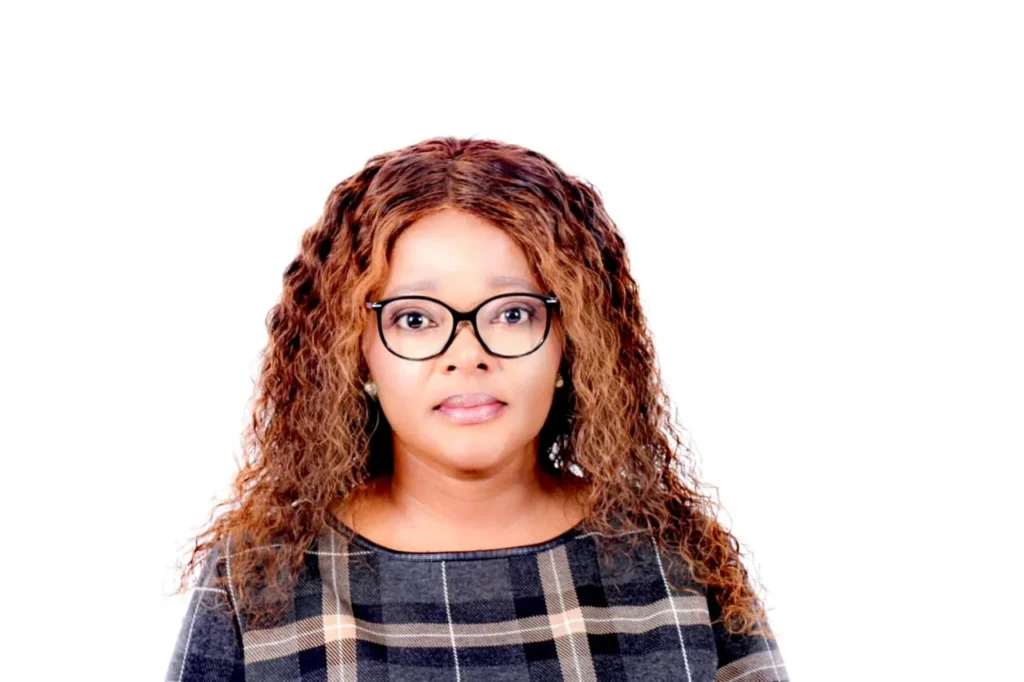
Lebo Letsoalo, founder of the African Women in Supply Chain Association (AWISCA)
The harmonisation panel will include Jonathan McDonald, Vice Chairman of the SA Freight and Logistics Association (SAFLA), and Prisca Mayumbelo CMILT, Chairperson of CILT Namibia and a transport and urban mobility specialist. Topics include vehicle standards, customs documentation, trade facilitation systems and mutual recognition of licences, permits and professional qualifications.
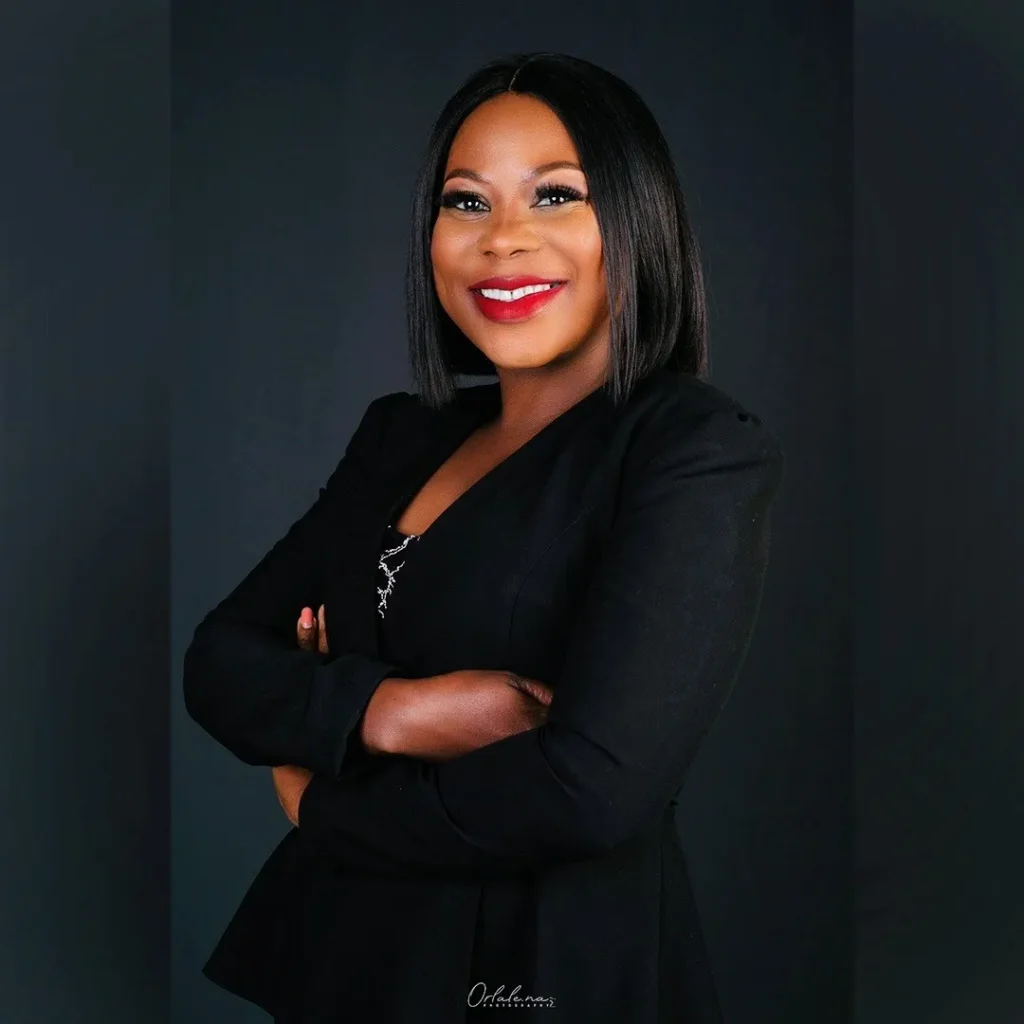
Prisca Mayumbelo CMILT
“By uniting Namibia, South Africa and Zimbabwe at Automechanika Johannesburg, we are turning policy aspirations into operational realities that will accelerate trade efficiency along our shared economic corridors,” states Mayumbelo.
Safer Operations and a Future-Ready Workforce
Day two will bring a regional perspective from Dr Tapiwa Mujakachi, President of CILT Zimbabwe, followed by a keynote on generative engine optimisation from Francois Vorster, Chief Disruptor at IMS.
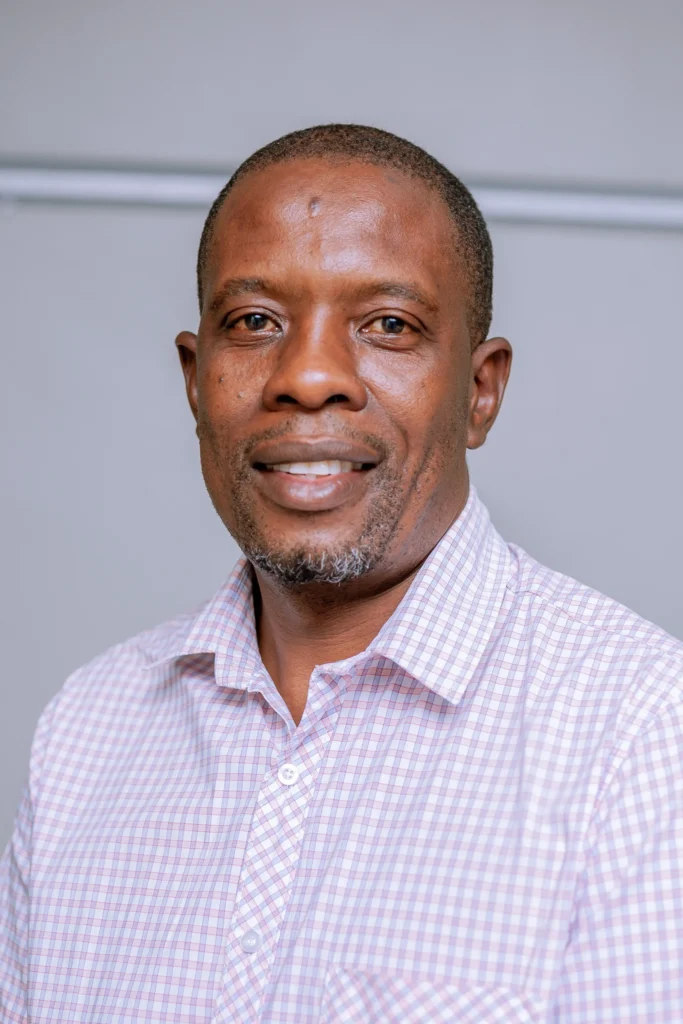
Dr Tapiwa Mujakachi, President of CILT Zimbabwe
Dr Mujakachi emphasises the collective purpose driving regional collaboration. “This three-way partnership demonstrates that our logistical challenges and economic destinies are deeply interconnected. Bringing our institutions and practitioners together allows us to co-create practical solutions that lower the cost of doing business and build corridor resilience for our shared future.”
The safety and security panel will include Gavin Kelly, CEO of the Road Freight Association (RFA) and Gerhard van Zyl, Group Operations Director at Professional Risk and Asset Management.
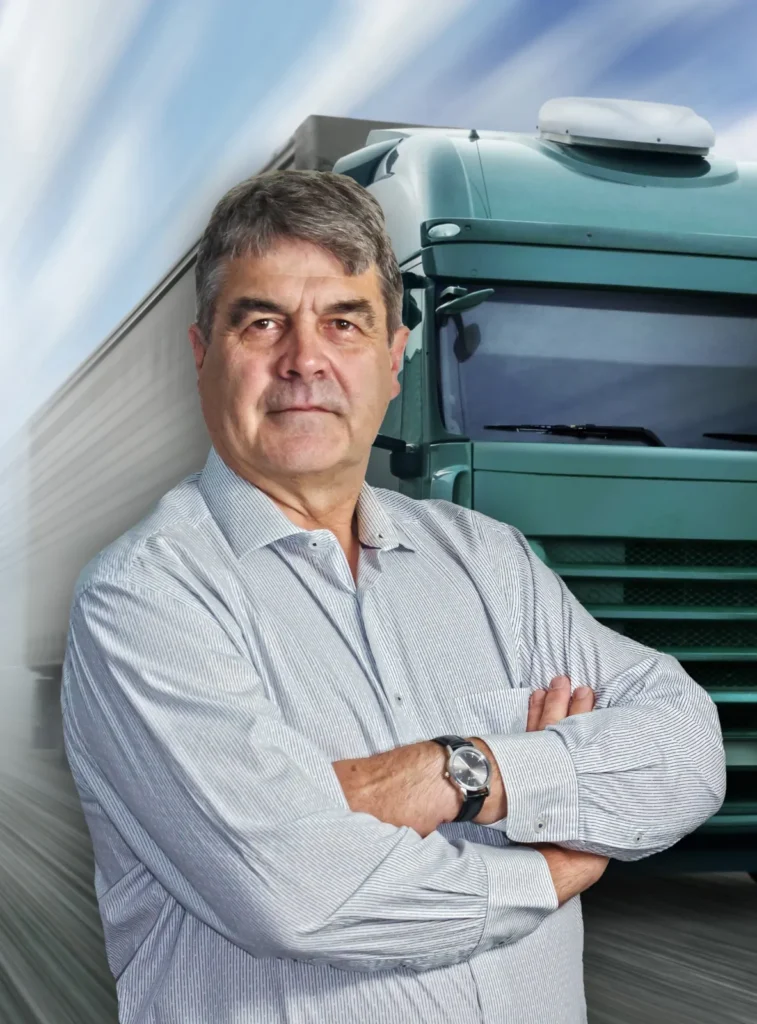
Gavin Kelly, CEO of the Road Freight Association (RFA)
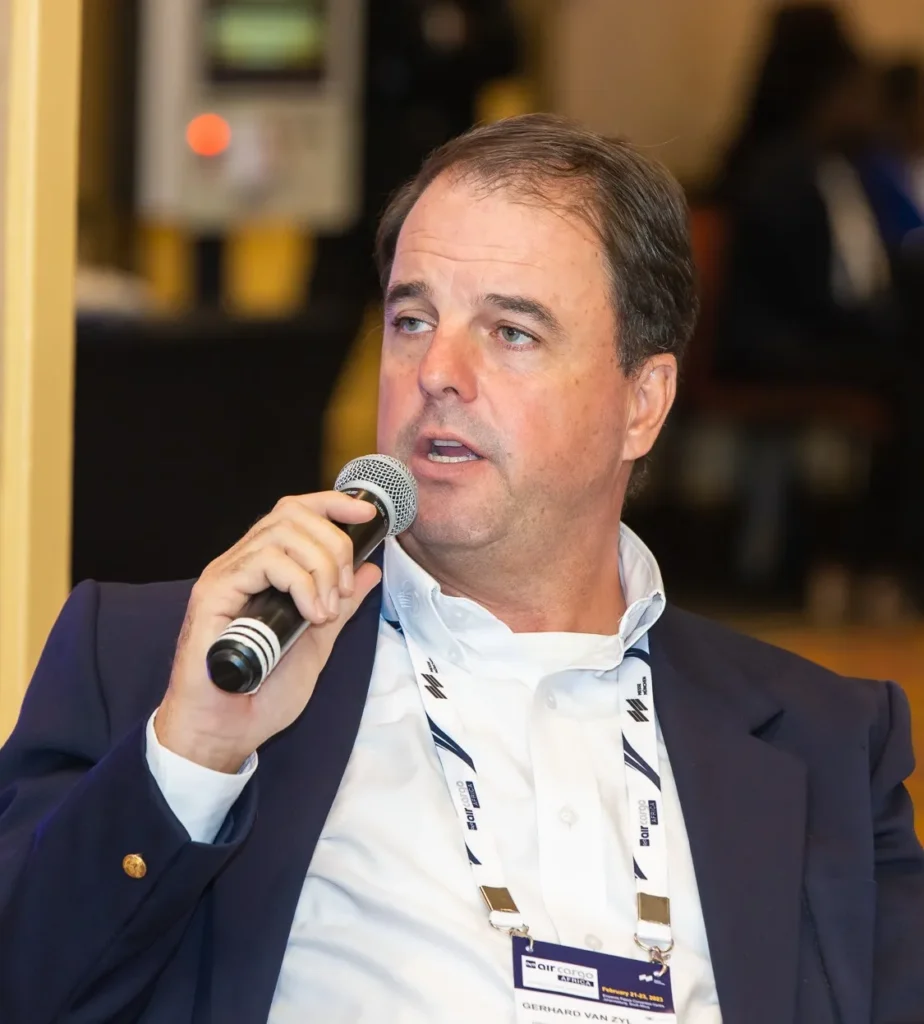
Gerhard van Zyl, Group Operations Director at Professional Risk and Asset Management.
The education, training and skills panel will feature Maphefo Ano Frempong, CEO of the Transport Education Training Authority (TETA); Anton Fiets, Executive: Industry Development at the Automotive Industry Development Centre (AIDC); Professor Chengedzai Mafini, Executive Dean at Vaal University of Technology; Ronald Mlalazi, CEO of Commerce Edge; and Sandile Khoza, CEO of COSA Holdings and CILTSA Council member.
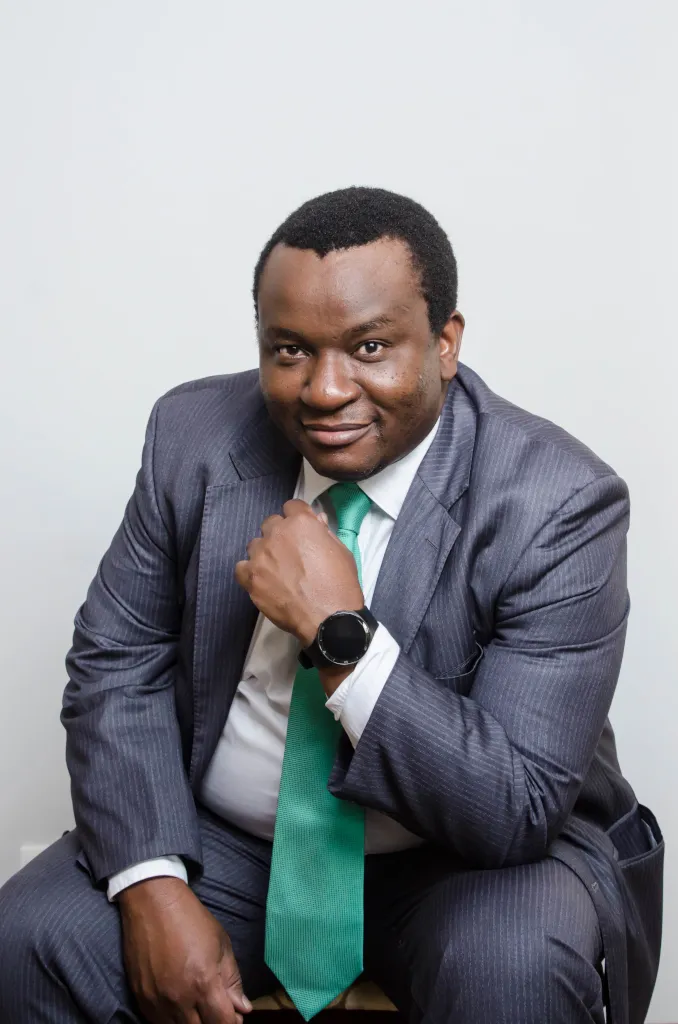
Sandile Khoza, CEO of COSA Holdings and CILTSA Council member
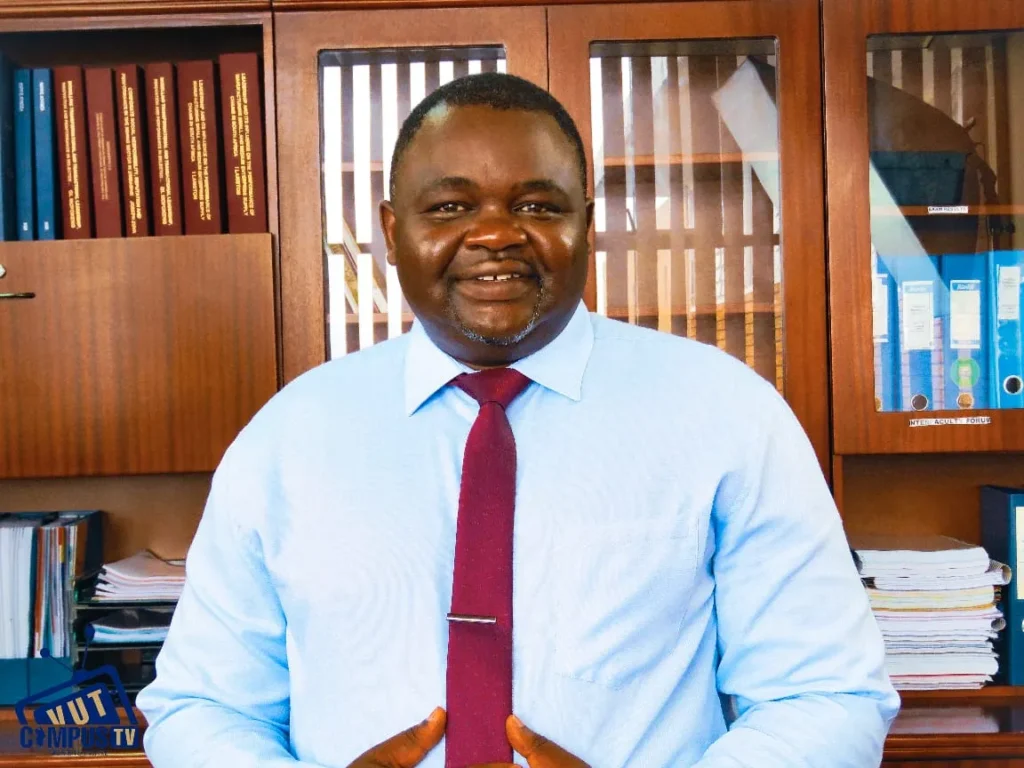
Professor Chengedzai Mafini, Executive Dean at Vaal University of Technology
Ronald Mlalazi, CEO of Commerce Edge
Formal sessions will be followed by lunch and dedicated opportunities to visit the Automechanika exhibition and network with exhibitors.
For more information about the conference or to register, visit: https://www.ciltsa.events/cilt-conference-at-automechanika-johannesburg/
Logistics
Hammer Blow to Road Freight Logistics With October Fuel Price Hike: What This Means for the Road Logistics Sector and Consumer
By Gavin Kelly, CEO of the Road Freight Association
Higher Fuel Prices Pushes Transport Costs Through the Roof
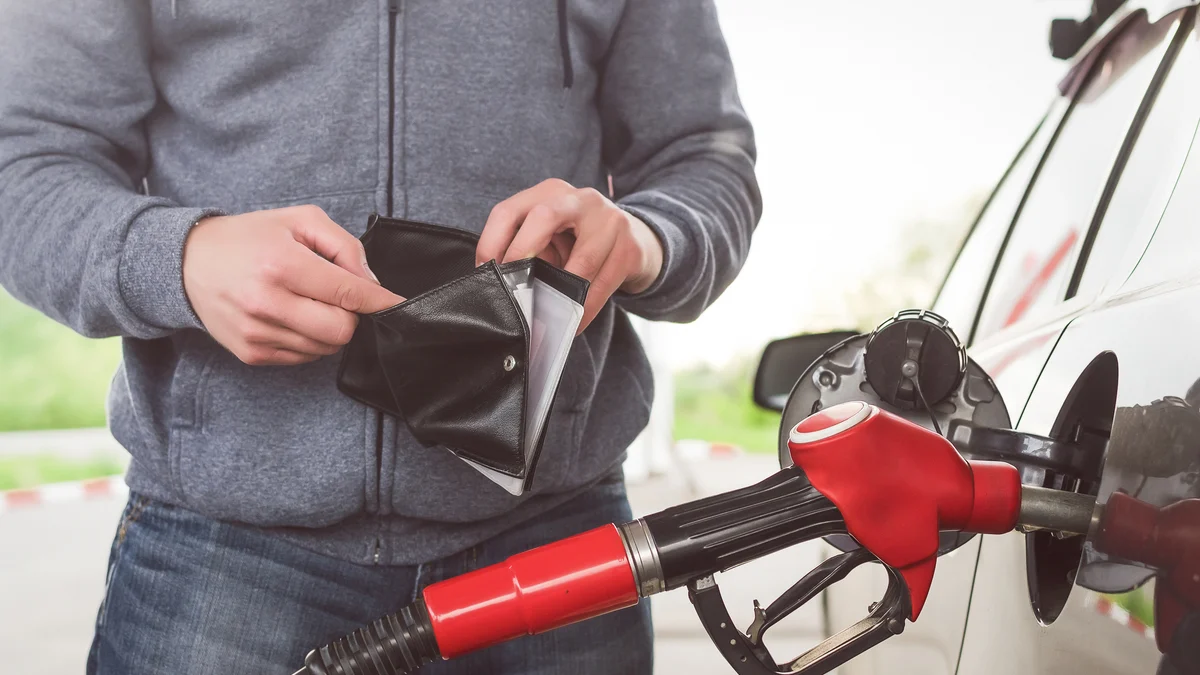
Every litre of fuel consumed on South Africa’s roads reflects the underlying health of the country’s logistics economy. Changes in fuel prices have a far-reaching effect on the country’s supply chain, transport systems, the wider logistics industry as well as the pricing of goods on store shelves.
The October increase in the price of fuel reminds everyone – especially the consumer – of just how exposed the broader logistics sector is to the volatility of global oil markets. With fuel prices continuing to rise, transport companies will inevitably raise the cost of transport due to increasing pressure on operational costs.
Depending on the type of operation, routes, vehicles and specific conditions of the transport leg, fuel can be anywhere between 35% and 55% of operating costs. Fuel is one of the three largest operating costs in the transport industry, thus even small price fluctuations can have significant consequences. South Africa moves more than 80% of the land-based freight via road freight (and a large amount of the general freight on rail also uses diesel) – one can understand that highly volatile fuel prices have an effect far beyond the road freight industry.
Diesel at the Heart of Freight Costs
The October fuel price adjustment sees petrol increasing to R29,88 and R30,25 per litre (inland) which is respectively a 11,6% and 12% per litre increase, whilst diesel increases by R2,84 and R3,24 per litre, depending on the amount of sulphur – resulting in a 10% or 11% increase on the base fuel cost of between 35% and 55%.
Diesel fuels a great majority of freight movement in the country, from line haul trucks that link ports and distribution centres to small delivery vehicles supplying local markets.
Since almost every sector depends on road freight, the changes in diesel prices have an exponential and expanded effect on the logistics industry and, unfortunately, the impact of fuel costs is inevitable.
As noted earlier, fuel is one of the biggest variable expenses and it impacts both short- and long-distance operations – it affects all legs in a logistics chain, and some transporters will now face severe cash flow constraints.
Global Pressures Shaping Local Fuel Prices
Global fuel market dynamics play an enormous role in determining fuel prices – supply and demand remains very relevant in what the (global) customer is prepared to pay for a barrel of oil, as well as the perceived shortage that drives a buying spree and thus the price for a barrel. Secondly, as oil is primarily bought with US Dollars, the value of the Rand against the Dollar plays a further (in our case) negative role in resulting in more expensive fuel at the pump.
Unfortunately, the majority of the petroleum products (crude oil and refined petroleum products) consumed in South Africa is imported, and this directly results in the domestic fuel cost either rising or falling.
The October increase was primarily caused by increasing global oil prices, geopolitical concerns, a weakening Rand and the growing instability in the global supply of energy networks. The political turmoil in major oil producing countries has now caused increased volatility to the market, which has led to worries about possible interruptions to the major distribution and transportation routes.
Oil markets typically react quickly to geopolitical risks, pushing crude prices higher and driving up the cost of refined fuel products downstream. For an economy like South Africa that imports oil, the outcome is often inevitable: higher domestic energy prices.
The Ripple Effect Across Logistics
Again, the fuel price increase does not end at the pump price – once fuel prices increase, the cost of moving goods from production sites to distribution centres, and finally to retailers is all exposed to price increases.
Road freight plays a crucial role in the long-distance moving of goods among ports, factories, warehouses, and retail locations.
Freight companies need to remain financially viable, and thus transport companies must choose whether to increase their rates (by a variety of factors of either full fuel price increase or a percentage thereof), or whether they have the financial reserves to withstand the increases. The latter will place pressure on cashflow and reserves. Rate adjustments are often inevitable due to the recurring fuel price strain, even if some transport operators may temporarily withstand the cost to preserve contracts and relationships with clients.
How Operators Are Managing Volatility
The transportation sector has grown increasingly defined by the volatility of fuel prices, and many transport companies adjust by reducing the volume of fuel used – fleet managers lever telematics technology, fuel choice, optimal routing software, driver training, new engine / vehicle technologies, congestion and standing time minimisation / avoidance and even load sharing.
Environmentally friendly driving techniques, better vehicle maintenance, and more sophisticated logistics planning are now essential resources for controlling operating expenses.
Fuel adjustment methods have been incorporated in several transport contracts, enabling operators to partially compensate for the rapid price changes without disrupting long-term commitments. These approaches may reduce the effects of the rising fuel prices; however, they are not sufficient to eradicate them.
Navigating an Uncertain Road Ahead
The fuel price increase illustrates how vulnerable the country’s transport sector is to international energy trends.
Unfortunately, it is difficult to completely rule out further fuel price increases – already there are indicators are that South Africa is heading towards further fuel price increases in November, should the tensions in the Middle East not be resolved. The ongoing geopolitical tension and the surge in risk, coupled with the supply and demand factor, adaptability will continue to be vital for South Africa’s freight sector.
Transport companies’ strategies for navigating this increasingly unstable operating environment will continue to be shaped by limiting fuel use, enhancing operational efficiency, and preparing for unpredictability.
One thing is certain: In a country that is dependent on road freight, such as South Africa, every adjustment in the price of diesel has consequences extending past the petrol pump, it goes deep into the transport systems that keep the country running.
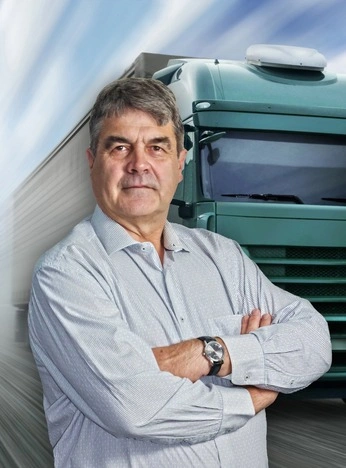
Gavin Kelly, CEO of the Road Freight Association

Can Your Business Handle 22% More Online Orders?

CILT Conference to Explore Innovation and Cross-Border Connectivity at Automechanika Johannesburg

A Game-Changer in South Africa’s Port Structural Reform


-
 Management3 months ago
SEO, AEO, GEO and SEO for AI: What Is the Difference for the Supply Chain Industry?
-
 Transport4 months ago
LDV T60 Max vs GWM P500 vs Isuzu D-Max vs Toyota Hilux vs Ford Ranger: Which Double-Cab Bakkie Offers the Best Value?
-

 Logistics4 months ago
DHL Group to invest around € 160 million in 2026-2027 to strengthen logistics infrastructure and support clean energy transition in France
-

 Logistics4 months ago
Top 5 Warehousing and Logistics Companies in the Western Cape by Google Review Rating
-

 Logistics4 months ago
DHL Expands Asia Pacific Data Center Logistics Capabilities to Support Growing Regional Demand
-

 Logistics4 months ago
Top 10 Warehousing and Logistics Companies in Gauteng by Google Review Rating
-

 Freight Forwarding4 months ago
The Hidden Cost of Shipping from China to South Africa — What Every SA Importer Needs to Know in 2026
-

 Logistics3 months ago
Top 4 Lift Truck Companies in Gauteng